
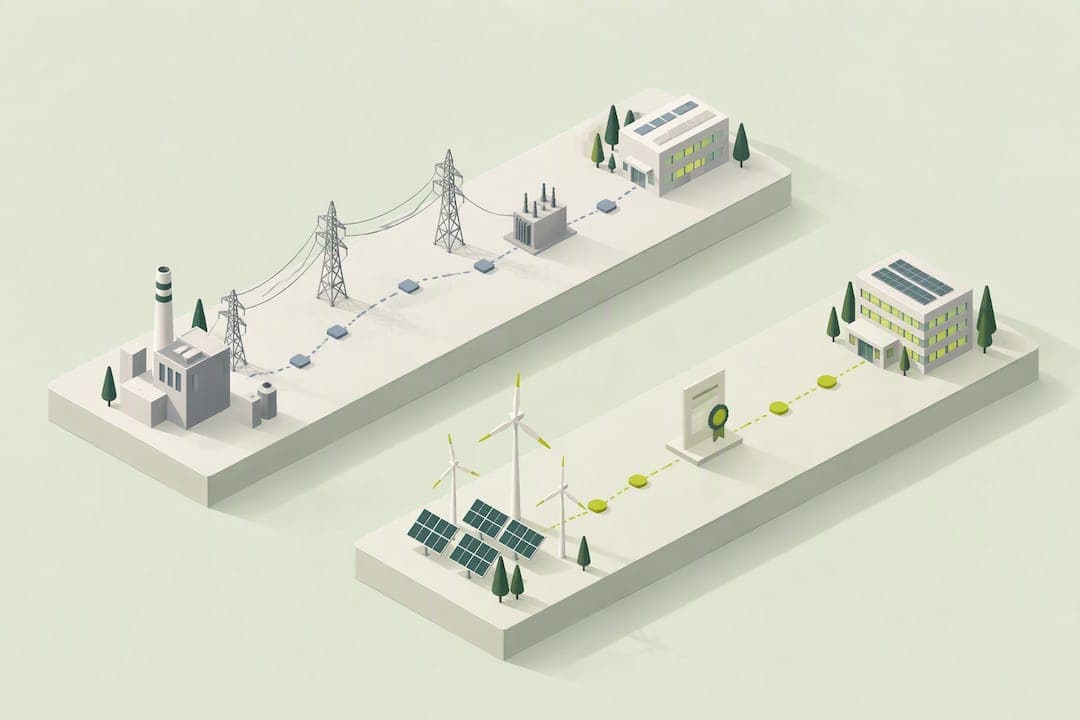
Scope 2 emissions are the indirect emissions created when we buy electricity, heat, steam, or cooling from an outside supplier rather than generating it ourselves. Where contractual instruments like Guarantees of Origin or power purchase agreements exist, reporters must calculate and disclose both a location-based and a market-based total. Getting there starts with clean activity data and the right emission factors for each method.
TL;DR:
- When contractual instruments are used, disclose separate location based and market based totals; uncovered consumption must use the residual mix factor.
- Renewable certificates can put market based totals 30% to 80% below grid averages, but only if they meet quality rules and match reporting periods.
- Pair site level meter or billing data with the correct factor and reporting period, and document instrument validity, coverage, and audit evidence.
- Efficiency measures, including lighting upgrades, HVAC controls, and better scheduling, reduce both totals because they lower energy use under either accounting method.
- For onsite generation, retaining its energy certificates preserves a low market based factor; selling them means that consumption falls back to the residual mix.
Table of Contents
- What Scope 2 Covers and How to Set the Inventory Boundary
- Location-Based vs Market-Based Methods: What Each One Measures
- Step-by-Step Calculation for Location- and Market-Based Scope 2
- What Standards and Regulations Require for Scope 2 Disclosure
- Actionable Strategies to Reduce Scope 2 and Their Reporting Impact
- How a Data Platform Supports Scope 2 Accounting
- What Sustainability Teams Should Do Next
- Get Consolidated Scope 2 Data Without the Spreadsheet Work
- FAQ
- Sources
What Scope 2 Covers and How to Set the Inventory Boundary
Scope 2 covers four purchased energy forms: electricity, heat, steam, and cooling. Any site that draws these from a grid, district network, or third-party supplier records consumption here, usually pulled from utility bills or meter data.
The boundary question trips up a lot of teams. If a facility generates and consumes its own power on site with no grid connection, that energy use sits outside Scope 2 entirely because there is no purchase transaction. The moment energy is bought, acquired, or drawn from a shared network, it belongs in Scope 2.
- Electricity, heat, steam, and cooling purchased from an external source all count toward Scope 2.
- Self-generated energy that is produced and consumed on site, with no purchase involved, is not recorded under Scope 2.
- Transmission and distribution losses and the upstream emissions from fuel extraction and processing sit in Scope 3, not Scope 2, because grid emission factors represent generation-only emissions.
Getting this boundary right matters because misclassifying T&D losses or upstream fuel impacts as Scope 2 inflates one category and understates another, which throws off both target-setting and year-over-year comparisons.
Location-Based vs Market-Based Methods: What Each One Measures
The two methods answer different questions, and conflating them is the most common reporting error we see.
The location-based method reflects the average emissions intensity of the grids where energy consumption occurs, typically drawn from national or regional grid-average factors such as the UK Government's own conversion figures. It tells us the physical reality of the electricity flowing into our meters, regardless of what we have contracted to buy.
The market-based method reflects the emissions associated with the specific energy we have purchased, using supplier-specific emission factors or contractual instruments like Energy Attribute Certificates, Guarantees of Origin, or power purchase agreements. It tells us whether our procurement choices are actually lowering our footprint.
- Location-based: uses grid-average or national emission factors, independent of any contracts.
- Market-based: uses emission factors tied to specific contractual instruments, or falls back to the residual mix when no instrument covers that consumption.
- Both figures must be disclosed side by side under the GHG Protocol Scope 2 Guidance, because location-based exposure and market-based procurement performance are not interchangeable.
The market-based figure can run 30% to 80% lower than the location-based figure when a reporter holds high-quality renewable instruments, a gap that shows up in reconciliation reports and surprises boards unfamiliar with dual reporting.
Watch for three recurring pitfalls: instruments that fail the GHG Protocol's Scope 2 Quality Criteria, contract periods that don't match the reporting year, and consumption left uncovered by any instrument that gets calculated with a supplier factor instead of the correct residual mix.

Step-by-Step Calculation for Location- and Market-Based Scope 2
Both totals follow the same basic arithmetic: activity data multiplied by an emission factor, with results expressed in metric tonnes of CO2e.
- Collect activity data by site and billing period, using half-hourly meter data where it's available for the most accurate time alignment.
- Select the correct emission factor: UK Government conversion factors for the location-based calculation, and the relevant contractual instrument factor, supplier-specific factor, or residual mix for the market-based calculation.
- Multiply activity data by the chosen factor, then apply global warming potential values to convert any non-CO2 gases into CO2e.
- Aggregate results by site and label each total clearly by method, noting the instrument type and the share of consumption it covers.
Pro Tip: Keep a running log of which sites have valid instruments and which default to the residual mix, since that single detail explains most of the gap between your two totals.
Before locking in numbers for disclosure, check four things: that activity data periods align with your instrument periods, that every instrument claimed is still valid and not double-counted elsewhere, that the coverage share is documented site by site, and that there's an audit trail linking each figure back to its source bill or certificate. A meter-to-report governance checklist helps catch gaps before they reach an assurance provider.
What Standards and Regulations Require for Scope 2 Disclosure
Dual reporting isn't optional once contractual instruments are in play. Both the GHG Protocol Scope 2 Guidance and the ESRS E1 Delegated Act require gross Scope 2 emissions to be shown as separate location-based and market-based totals, with disaggregation where relevant.
For the location-based figure, UK reporters should use the 2026 UK Government greenhouse gas conversion factors, published June 11, 2026. These factors are updated annually, and the accompanying major changes report flags any year-on-year revision greater than 5%, which can shift a site's location-based total meaningfully even with unchanged consumption.
Disclosure should include:
- The calculation method used for each total (location-based, market-based).
- The type and volume of contractual instruments applied, plus the share of consumption each one covers.
- The residual mix factor used for any uncovered consumption.
- Documentation sufficient for an assurance partner to verify instrument validity and avoid double counting.
Actionable Strategies to Reduce Scope 2 and Their Reporting Impact
Reduction work splits into two tracks that behave differently in the two accounting methods.
Efficiency and demand reduction, lighting upgrades, HVAC controls, better scheduling, and lower total consumption reduce emissions regardless of method, since both totals start from the same activity data. This is the safest place to start because the benefit shows up everywhere.
Onsite generation is more nuanced. Keeping the Energy Attribute Certificates tied to that generation lets us claim its low emission factor in market-based reporting; selling those certificates means we must fall back to the residual mix for that consumption, even though we generated it ourselves.
Procurement choices, green tariffs, power purchase agreements, EACs or Guarantees of Origin, only strengthen a market-based claim when they meet the GHG Protocol's Scope 2 Quality Criteria. A renewable certificate reconciliation process tied to half-hourly consumption data is what makes that claim defensible under scrutiny.
- Efficiency measures reduce both location-based and market-based totals together.
- Retaining EACs from onsite generation preserves the low market-based factor; selling them does not.
- Procurement must meet Quality Criteria to count credibly toward a market-based reduction claim.
Pro Tip: Sequence the work: fix data governance first, then efficiency, then procurement, so each investment is measured against accurate baselines rather than estimates.
How a Data Platform Supports Scope 2 Accounting
Reconciling activity data, instruments, and factors across multiple sites by hand is where most Scope 2 reporting errors creep in. We built EnerlyticsAI to close that gap directly.
- Half-hourly consumption analytics give the time-aligned activity data both calculation methods need.
- Automated bill validation catches billing errors before they distort a site's activity figures.
- Multi-site consolidation brings every location's data into one carbon report covering Scope 1, 2, and 3.
- EAC reconciliation matches certificates to the consumption periods they actually cover, supporting a defensible market-based total.
Access to the core platform is available without upfront charges, enabling management of multiple sites and facilitating consolidated, audit-ready Scope 2 figures.
What Sustainability Teams Should Do Next
Start with an audit of meter data and energy contracts site by site, then compute both the location-based and market-based totals rather than picking one. Document every instrument used, including the share of consumption it covers, and prioritize efficiency work before procurement changes, since efficiency moves both numbers at once.
Keep an eye on GHG Protocol revisions and the annual UK conversion factor update each year. When presenting to a board or an assurance partner, bring both totals and the instrument documentation behind them, not just the more favorable number.
— Chris
Get Consolidated Scope 2 Data Without the Spreadsheet Work
We built EnerlyticsAI to take the manual reconciliation out of Scope 2 reporting. Half-hourly consumption analytics, automated bill validation, and multi-site consolidation mean the activity data behind both your location-based and market-based totals is ready whenever you need to report.
Our core platform can be used across multiple sites with no upfront cost. Start with the free plan or review what our Emissions reporting tools cover before your next disclosure deadline.
FAQ
What are Scope 2 emissions?
Scope 2 emissions are the indirect emissions created when we purchase electricity, heat, steam, or cooling rather than generating it ourselves. They are calculated two ways, location-based and market-based, and both figures are typically reported together when contractual instruments are in use.
What are Scope 1, Scope 2, and Scope 3 emissions?
Scope 1 covers direct emissions from sources we own or control, like company vehicles or on-site boilers. Scope 2 covers indirect emissions from purchased energy, and Scope 3 covers all other indirect emissions across our value chain, including upstream fuel production and transmission losses tied to our energy use.
What is the difference between Scope 2 and Scope 3 emissions?
Scope 2 covers the emissions from the electricity, heat, steam, or cooling we purchase and consume directly. Scope 3 covers everything else in the value chain, including the upstream emissions from producing that fuel and the transmission and distribution losses that occur before the energy reaches our meter.
How do I calculate Scope 1, 2, and 3 emissions?
Each scope follows the same basic formula: activity data multiplied by an emission factor, converted to CO2e using global warming potential values. For Scope 2 specifically, that means pairing metered or billed consumption with either a grid-average factor for the location-based total or a contractual instrument factor for the market-based total.
Sources
- GHG Protocol Scope 2 Guidance
- 2026 Government greenhouse gas conversion factors for company reporting
- 2026 GHG conversion factors: major changes report
- ESRS E1 Delegated Act — Disclosure Requirements